Wall Street’s IPO Bloodbath: The Biggest Listings of 2026 Lose 20% as the AI Frenzy Fades
 ΧΡΟΝΟΣ ΑΝΑΓΝΩΣΗΣ 15 '
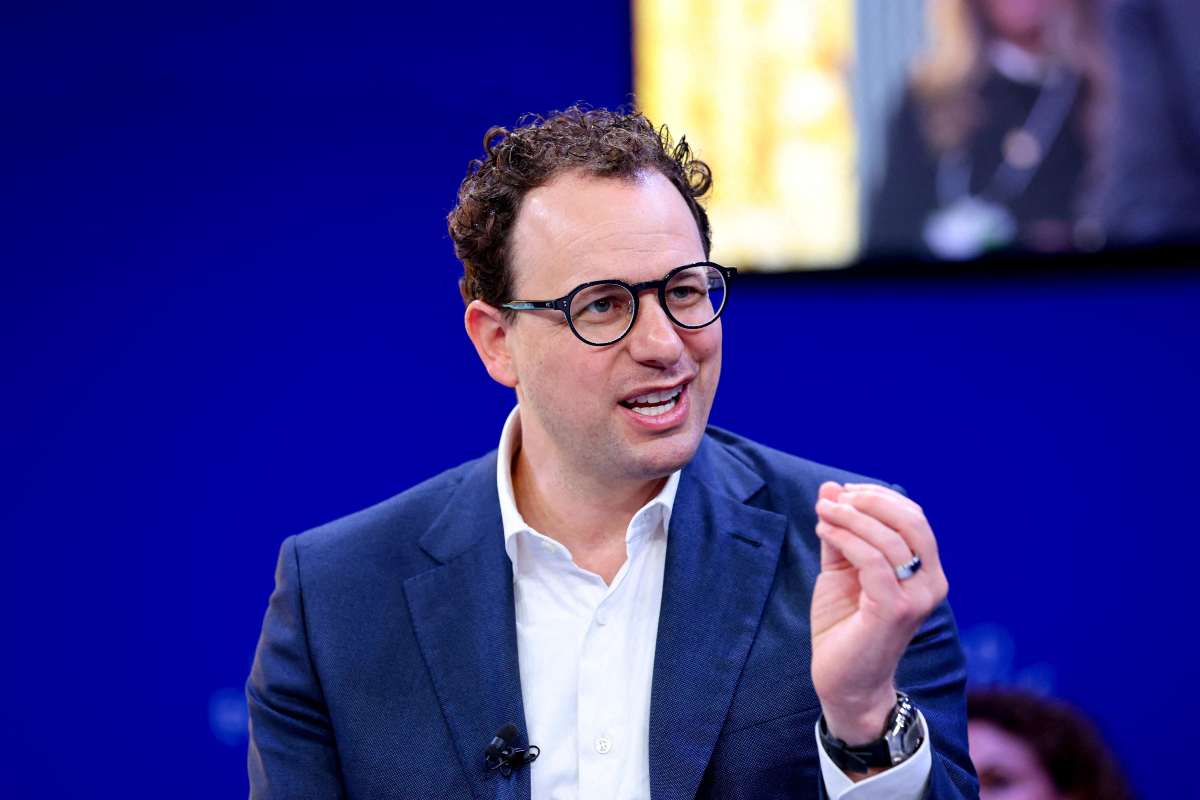
Πηγή Φωτογραφίας: Dario Amodei – Anthropic Editorial imagery: Getty Images.


The artificial intelligence boom has generated extraordinary fortunes for technology founders, investment bankers and early-stage investors. But for many investors buying into Wall Street’s biggest initial public offerings, 2026 has delivered a very different outcome: substantial losses.
According to an analysis published by the Financial Times on November 16, the ten largest US IPOs of the year have declined by an average of 20.5% from their offering prices, marking a striking reversal after four consecutive years in which investors in the largest flotations had generally enjoyed positive returns.
The figures reveal an increasingly uncomfortable reality for Wall Street. The market for new listings has surged to its highest level of the decade in terms of capital raised, yet the performance of many newly listed companies has disappointed.
And now, with artificial intelligence developer Anthropic preparing for one of the largest stock market debuts in history, the financial industry faces a crucial question: has the AI investment boom reached the point where investors are no longer willing to pay almost any price for future growth?
A Record IPO Boom That Has Left Investors Nursing Losses
The reopening of America’s IPO market was supposed to mark a new chapter for global equities.
After years of uncertainty, higher interest rates and subdued listing activity, 2026 brought a wave of major companies seeking public-market financing.
The return of large-scale flotations was particularly significant for technology businesses, many of which had benefited from the extraordinary enthusiasm surrounding artificial intelligence, advanced computing and digital infrastructure.
But the results have been disappointing.
The Financial Times found that the ten biggest IPOs of 2026 had lost an average of 20.5% relative to their initial offering prices.
That performance contrasts sharply with the previous four years.
Even in 2022, when the S&P 500 declined by 19.4%, investors who bought shares in the ten largest US IPOs at their offering prices would still have recorded positive returns by year-end.
One senior executive at a major US asset manager described the situation in unusually stark terms:
“IPO performance has been awful this year — the class of 2026 has produced very little.”
The executive also warned that the approaching Anthropic listing presents a significant risk for fund managers attempting to protect their annual investment performance.
“If Anthropic doesn’t go well, it could screw up my entire year.”
The concern reflects a broader shift in market psychology.
Investors who were previously eager to secure allocations in high-profile flotations are becoming increasingly selective, particularly when companies arrive on the stock exchange with aggressive valuations and uncertain long-term profitability.
SpaceX: Even Elon Musk’s Blockbuster IPO Has Lost Its Momentum
One of the most striking examples is SpaceX, Elon Musk’s aerospace and satellite company.
Its flotation was the largest of 2026 and attracted enormous attention from institutional and individual investors.
Initially, the stock surged, reinforcing expectations that the company could become one of the most successful new listings in recent history.
But the enthusiasm proved difficult to sustain.
Within days of its debut, SpaceX shares retreated sharply. Over much of the past month, they have traded close to their original offering price of $135 per share.
The reversal illustrates a growing challenge for the market.
Even businesses with exceptional brand recognition, powerful founders and ambitious long-term growth prospects are struggling to maintain the valuations investors initially assigned to them.
The issue is not necessarily a deterioration in the underlying business.
Rather, investors are questioning whether the prices demanded at flotation already incorporate years of anticipated growth, leaving limited room for further gains.
SpaceX has become an important example of that tension: a high-profile company whose initial market excitement has not translated into sustained share-price appreciation.
Too Much Money Chasing Too Many Deals
The weakness in newly listed companies is not attributable solely to concerns about artificial intelligence.
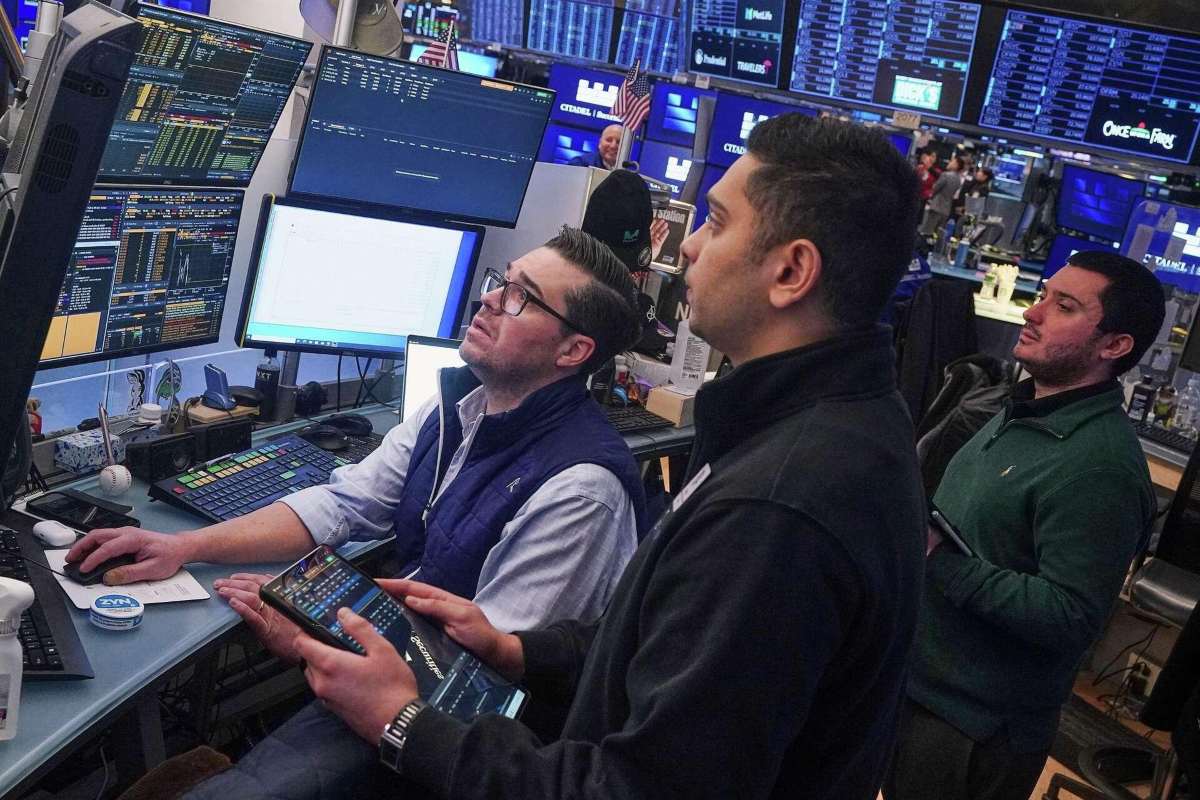
Wall Street is also facing an extraordinary volume of securities issuance.
Alongside the surge in IPOs, companies have been raising additional equity through follow-on offerings, while major technology groups have issued substantial amounts of debt to finance their expansion.
The combined supply of new shares and bonds is placing pressure on investors’ capacity and willingness to absorb additional risk.
Sanjay Rijhsinghani, chief investment officer at LGT Wealth Management, highlighted this growing market fatigue.
“There is just so much issuance going on in the bond and equity market.”
He added:
“There is a bit of fatigue.”
The warning is particularly relevant to the technology sector, where enormous investment programmes are competing for capital.
Artificial intelligence infrastructure requires expensive data centres, advanced semiconductors, electricity generation, cooling systems and communications networks.
As companies continue to raise money to finance these investments, institutional investors must decide how much exposure they are willing to maintain to the same underlying growth narrative.
The result is an increasingly crowded market in which even attractive businesses can struggle to generate positive returns for new shareholders.
The AI Valuation Problem: Investors Are Buying a Future That May Never Arrive
Perhaps the most important concern is the widening gap between artificial intelligence valuations and the financial returns those businesses can demonstrate.
Many AI-related companies are being valued according to projections of enormous future revenues rather than established profitability.
That approach can work when growth expectations are continually exceeded.
It becomes far more problematic when investors begin questioning whether the industry’s massive capital expenditure will produce adequate returns.
Rijhsinghani captured the dilemma:
“None of these IPOs are coming at bargain-basement prices.”
He also warned that the businesses are inherently difficult to assess.
“You’re buying a future price which may or may not materialise.”
The concern extends across the AI ecosystem.
Technology companies are spending heavily on computing capacity, while chipmakers and infrastructure providers are attempting to meet unprecedented demand.
Yet the eventual profitability of these investments remains uncertain.
Investors increasingly want evidence that AI adoption can generate sustainable cash flows, rather than simply justify another round of expensive infrastructure development.
This represents a potentially significant turning point.
For much of the AI boom, the dominant question was how quickly companies could expand.
Now the market is beginning to ask how much money they can actually earn from that expansion.
Anthropic’s $1.4 Trillion Test: The IPO That Could Define the Market
The next major test arrives this week.
Anthropic, the developer of the Claude artificial intelligence models, is preparing for one of the largest initial public offerings in stock market history.
The company has outlined plans to sell 825 million shares at an indicative price of $70 to $78 each.
<text color=”default” weight=”medium”>At the upper end of that range, the offering could raise approximately $64.35 billion and imply a company valuation of as much as $1.4 trillion on the fully diluted basis reported by S&P Global Market Intelligence.</text>
The proposed valuation reflects the extraordinary expectations surrounding companies developing advanced generative AI systems.
Anthropic has attracted attention because it offers investors a relatively direct opportunity to gain exposure to a leading AI model developer, rather than investing indirectly through established technology giants.
Demand has reportedly been strong enough for the company’s investment bankers to consider increasing the offering price.
But that enthusiasm comes against an increasingly difficult market backdrop.
Investors are weighing the company’s rapid revenue growth against substantial operating losses, massive infrastructure commitments and the uncertainty surrounding the long-term economics of AI.
The proposed flotation is expected to be priced on November 18, with trading anticipated to begin on November 19, subject to regulatory clearance.
Its performance could become a closely watched indicator of whether investors remain willing to support the industry’s most ambitious valuations.
Why Anthropic Is Different – And Why the Risks Remain
Despite the disappointing performance of other major IPOs, Anthropic continues to attract significant investor interest.
The company occupies a distinctive position in the market.
Unlike diversified technology groups such as Microsoft, Alphabet or Amazon, Anthropic provides relatively concentrated exposure to the commercial development of frontier artificial intelligence.
That makes its shares potentially attractive to investors seeking direct participation in the AI industry.
Rijhsinghani described the appeal:
“Anthropic is the first pure-play AI stock.”
He added:
“We haven’t got anything else like that in the market.”
But the company’s distinctive position does not eliminate valuation risks.
Anthropic is entering the public markets during a period of considerable uncertainty about AI profitability, infrastructure spending and future regulation.
Its planned listing also follows a sharp October sell-off in semiconductor shares, driven partly by concerns that enormous spending on AI computing infrastructure may not generate sufficient financial returns.
The broader political environment has become more complicated as well.
Following the US midterm elections, investors have been assessing the possibility of stronger scrutiny of data-centre construction, energy consumption and the influence of large technology companies.
These developments are adding another layer of uncertainty to an industry already confronting questions about the sustainability of its investment cycle.
Wall Street’s New Strategy: Wait for the IPO Hype to Fade
The poor performance of this year’s largest flotations is changing how professional investors approach new listings.
Rather than rushing to participate in initial offerings, some asset managers are increasingly considering buying shares after companies have begun trading.
The strategy reflects a simple calculation: if newly listed shares frequently decline below their offering prices, waiting may provide a more attractive entry point.
John Ettinger, senior portfolio manager at Federated Hermes, said the number of disappointing large deals was exceptional.
“There are more big deals down a lot this year than I have seen at any point in my career.”
He suggested that maintaining available cash could allow investors to purchase attractive companies later at lower prices.
The shift is important because it could alter the balance of power between companies seeking to list and the institutions providing capital.
During periods of intense IPO enthusiasm, issuers and their investment banks can often demand aggressive valuations.
But when investors become more disciplined, companies may be forced to accept lower prices or delay their market debuts.
Ettinger nevertheless stressed that strong businesses can still attract investors.
“Good companies that are executing, growing, coming at a reasonable valuation are going to be able to get done in any market.”
The message is that investors are not necessarily abandoning technology or artificial intelligence.
They are becoming less willing to pay unlimited premiums for anticipated growth.
The Political Backlash Against AI Adds Another Layer of Risk
The financial uncertainty surrounding artificial intelligence is increasingly intersecting with politics.
The US midterm elections in early November strengthened Democratic representation in Congress, including candidates who campaigned against aspects of rapid data-centre expansion.
Their concerns include electricity costs, water consumption, environmental pressures and the impact of large technology infrastructure projects on local communities.
For investors, the possibility of stricter oversight creates another variable when assessing future AI profitability.
Data-centre expansion depends on access to affordable electricity, planning approvals, financing and specialised hardware.
Restrictions or delays affecting any of these areas could increase costs and complicate growth projections.
The market is therefore beginning to price not only technological and commercial uncertainty, but also political and regulatory risk.
This does not necessarily mean the AI expansion will reverse.
It does mean that the industry may face more difficult conditions than those assumed in some of its most ambitious financial projections.
Is the AI Bubble Bursting – Or Is Wall Street Finally Becoming Selective?
The disappointing performance of the largest IPOs raises an unavoidable question about the future of the AI investment cycle.
A decline in newly listed shares does not, by itself, prove that artificial intelligence is experiencing a speculative bubble.
IPO prices can fall for many reasons, including excessive initial valuations, market volatility, changes in interest rates and temporary imbalances between supply and demand.
But the scale of the 2026 underperformance suggests that investors are reassessing the prices they are prepared to pay for long-term growth.
The distinction between technological potential and financial returns is becoming increasingly important.
Artificial intelligence may continue transforming industries, improving productivity and generating new business models.
Yet those developments do not guarantee that every company associated with AI will justify its market valuation.
The experience of previous technological investment cycles demonstrates that transformative innovations can coexist with disappointing shareholder returns when companies are purchased at excessive prices.
That is the central tension now confronting Wall Street.
The AI revolution may still be in its early stages, but investors are becoming more demanding about the financial evidence supporting its most ambitious valuations.
The Next 72 Hours Could Reshape the AI Investment Narrative
With Anthropic approaching its expected market debut, Wall Street faces a particularly sensitive moment.
A successful flotation would demonstrate that investors remain willing to finance large AI companies despite recent volatility.
But strong demand at the offering stage would not necessarily guarantee positive returns once trading begins.
The experience of SpaceX and other major 2026 listings illustrates how quickly enthusiasm can fade after shares reach the public market.
For investment banks, the challenge is to price Anthropic aggressively enough to satisfy existing shareholders while leaving sufficient potential upside for new investors.
For asset managers, the question is whether the company’s growth prospects justify its enormous valuation.
And for the wider technology industry, the outcome could influence how other AI businesses approach future fundraising and stock market listings.
The biggest lesson of 2026 is becoming increasingly clear: Wall Street may still believe in the transformative power of artificial intelligence, but belief alone is no longer enough to guarantee investment returns.
The AI boom has not necessarily ended. What may be ending is the era in which investors were prepared to pay almost any price to participate in it.
Source: pagenews.gr
Διαβάστε όλες τις τελευταίες Ειδήσεις από την Ελλάδα και τον Κόσμο