EU Budget Bombshell: Corruption Could Become Harder to Detect — Greece Under the Spotlight
 ΧΡΟΝΟΣ ΑΝΑΓΝΩΣΗΣ 13 '
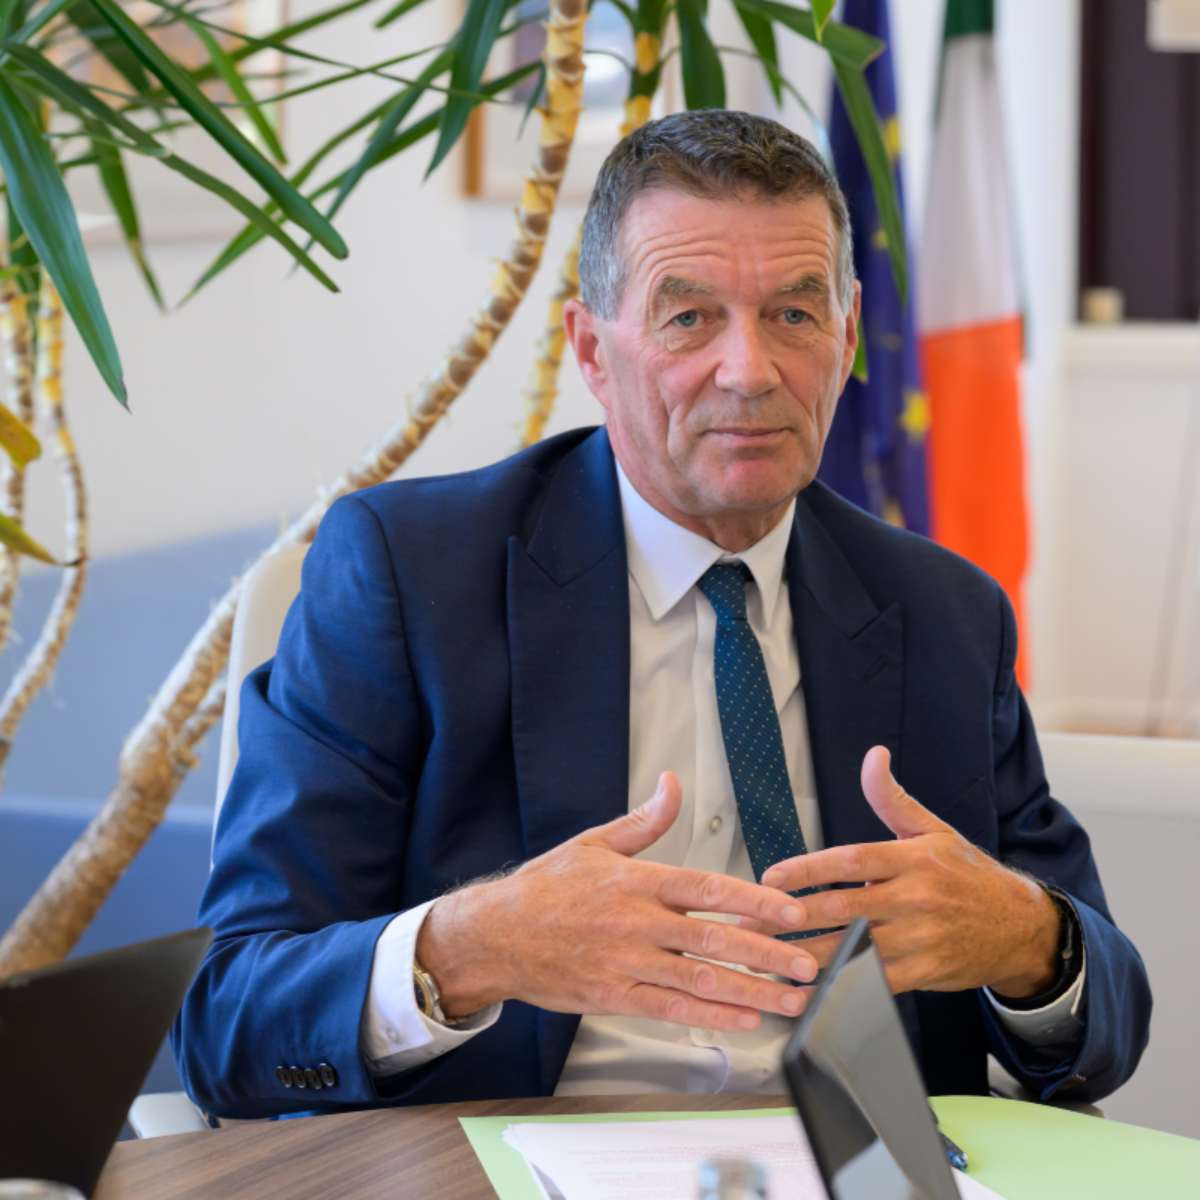
Πηγή Φωτογραφίας: AP Photo//EU Budget Bombshell: Corruption Could Become Harder to Detect — Greece Under the Spotlight


A major warning from the European Union’s top financial watchdog has intensified concerns over the future of transparency, accountability and anti-corruption safeguards in the bloc’s next long-term budget.
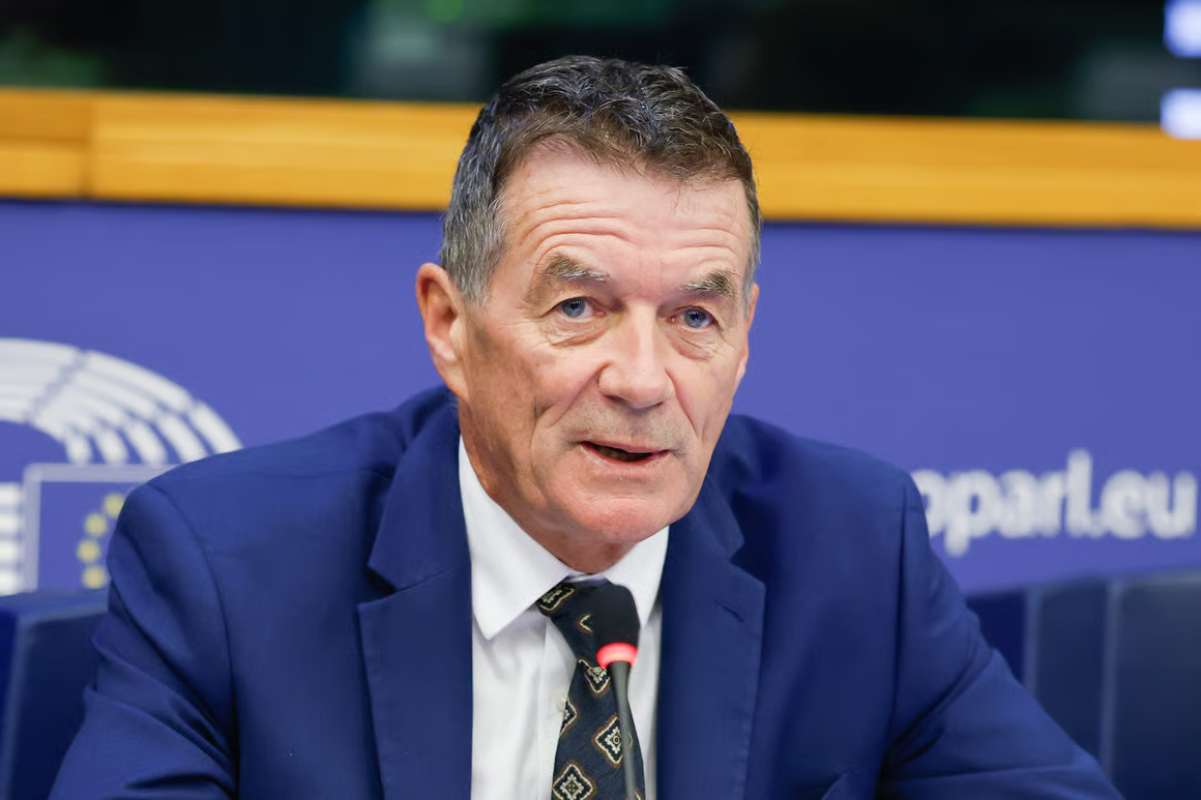
Tony Murphy, president of the European Court of Auditors (ECA), has warned that the European Commission’s proposed budget framework for 2028–2034 could make it more difficult to track how EU money is spent and identify potential irregularities.
Speaking to Politico, Murphy raised concerns that the Commission’s push for greater spending flexibility could weaken the ability of European auditors to follow public funds from Brussels to their final recipients.
The warning comes as EU governments prepare for negotiations over a proposed long-term budget worth approximately €2 trillion.
At the centre of the controversy is a fundamental question: can the European Union simplify its spending rules and give national governments greater flexibility without compromising financial oversight?
For Greece, where European agricultural subsidies and cohesion funds play a significant economic role, the debate carries particular importance.
Brussels’ New Budget Plan Raises Transparency Concerns
The European Commission wants to overhaul how major portions of EU funding are allocated and managed.
Under the proposed framework, several funding streams would be consolidated into broader National and Regional Partnership Plans, covering areas including agriculture, regional development, fisheries, migration and security.
The Commission argues that this approach would reduce bureaucracy, accelerate investment and allow governments to respond more effectively to changing economic and political priorities.
However, the European Court of Auditors fears that combining different spending programmes into broader national plans could make it harder to determine precisely where public money goes.
Murphy’s central concern is the ability to “follow the money” — a fundamental requirement for effective financial auditing.
If funding is distributed through increasingly complex national structures, auditors may face greater difficulties identifying final beneficiaries, verifying eligible expenditure and assessing whether EU resources have been used appropriately.
The issue is not simply administrative.
It concerns the European Union’s ability to demonstrate that taxpayers’ money is being spent lawfully and effectively.
Nearly €865 Billion Under a New Funding Structure
One of the most significant elements of the Commission’s proposal is the creation of a major funding instrument worth approximately €865 billion in current prices.
The instrument would bring together policies that currently operate through separate programmes and administrative arrangements.
Agricultural support, cohesion funding and regional development would be incorporated into a broader framework based on national and regional plans.
The Commission believes this structure would allow countries to shift resources more easily between priorities.
Payments would increasingly depend on agreed milestones, reforms and investment objectives.
Supporters of the reform argue that the current EU funding architecture is excessively fragmented.
They believe a more integrated system could improve efficiency and reduce administrative costs.
However, critics question whether a system based on broader objectives and national reporting would provide enough information to verify individual expenditures.
For the European Court of Auditors, the key challenge is ensuring that flexibility does not come at the expense of traceability.
Agricultural Subsidies at the Centre of the Debate
The proposed changes have triggered particular concern over the future of the Common Agricultural Policy (CAP).
Agricultural funding remains one of the European Union’s most important spending commitments.
It supports farmers, rural communities, environmental initiatives and agricultural investment across the bloc.
Under the existing framework, agricultural payments are subject to specific eligibility requirements, administrative checks and, where necessary, on-site inspections.
Integrating agricultural support into broader national plans could alter how these controls operate.
The European Court of Auditors is concerned that monitoring individual agricultural payments could become more complicated if funding is managed alongside several other policy areas.
The issue is particularly sensitive because agricultural subsidies often involve large numbers of beneficiaries and complex eligibility criteria.
Effective oversight requires reliable land registries, accurate declarations and systems capable of identifying inconsistencies.
Without such safeguards, greater administrative flexibility could increase the risk of irregular payments.
Greece’s Fake Pastureland Scandal Highlights the Risks
The debate has a direct connection to Greece.
In its reporting, Politico points to cases involving allegedly fraudulent agricultural subsidy claims linked to fictitious or improperly declared pastureland in Greece.
The cases illustrate how weaknesses in verification procedures can expose European agricultural funding to abuse.
The central concern is whether public authorities can reliably establish who controls agricultural land, whether the declared activity is genuine and whether applicants meet the conditions for receiving financial support.
The Greek cases do not demonstrate that the proposed EU budget has already caused corruption.
Rather, they provide an example of why strong controls are necessary when significant public funds are distributed through national administrative systems.
For Greece, the proposed budget reform therefore presents a dual challenge.
The country must protect funding for farmers and rural development while ensuring that national oversight mechanisms can prevent fraudulent or ineligible payments.
The credibility of agricultural funding depends not only on the amount of money available but also on whether it reaches legitimate beneficiaries.
Cohesion Funding Faces Similar Questions
Concerns about financial oversight extend beyond agriculture.
EU cohesion funds support infrastructure, employment, regional development, business investment and efforts to reduce economic disparities between member states.
These programmes frequently involve national ministries, regional authorities, contractors and private beneficiaries.
Combining different funding streams into broader plans could give governments greater discretion over investment priorities.
However, it could also make the allocation of responsibilities more complicated.
Auditors need to establish who approved a project, who received the money, whether the expenditure was eligible and whether the investment delivered the intended results.
For countries such as Greece, where cohesion funding remains a major source of public investment, maintaining transparent procedures is particularly important.
The challenge is to preserve the advantages of flexible funding while ensuring that financial accountability remains effective.
EU Auditors Report a 3.8% Error Rate
The warning comes against the backdrop of continuing concerns about irregularities in EU expenditure.
According to the European Court of Auditors’ annual report for the 2025 financial year, the estimated error rate in the EU budget’s audited spending reached 3.8%, compared with 3.6% in 2024.
The estimated value of expenditure affected by errors approached €5 billion.
However, an important distinction must be made.
An audit error is not automatically evidence of fraud or corruption.
Errors may result from ineligible expenditure, incorrect administrative procedures, missing documentation or failure to comply with programme requirements.
Fraud and corruption involve more specific forms of wrongdoing that require separate investigation and evidence.
Nevertheless, persistent errors raise questions about the effectiveness of financial management systems.
The ECA’s concerns suggest that any reform of EU spending should strengthen, rather than weaken, the ability to identify and correct irregularities.
The Recovery Fund Provides a Warning
The European Court of Auditors has also drawn attention to lessons from the EU’s Recovery and Resilience Facility.
Established in response to the Covid-19 pandemic, the Recovery Fund introduced a financing model linking payments to reforms, investments and agreed milestones.
The approach allowed governments to receive funding based on progress towards specific objectives.
However, auditors have repeatedly identified shortcomings in the availability of information about final recipients, actual costs and the results of certain investments.
These concerns are particularly relevant because the Commission’s proposed budget incorporates elements of a similar performance-based model.
Murphy’s warning is that weaknesses identified in the Recovery Fund should not be replicated across a much larger share of the EU budget.
A system that verifies whether a milestone has been completed must also provide sufficient assurance that the underlying expenditure is legitimate.
The two objectives are complementary, not interchangeable.
Can National Authorities Provide Reliable Oversight?
Another major issue concerns the growing responsibility of national governments.
Under the proposed framework, national authorities would play an increasingly important role in implementing and monitoring EU-funded programmes.
This raises questions about differences in administrative capacity, auditing standards and institutional independence across member states.
European countries do not operate identical financial management systems.
Some have more advanced digital monitoring tools, stronger administrative resources or more extensive verification procedures than others.
The European Court of Auditors has therefore emphasised the importance of retaining access to reliable financial information.
Independent European-level oversight is particularly important when funding is distributed through national systems with varying capabilities.
The central concern is whether Brussels will retain enough information and authority to verify that EU money is being used appropriately.
European Commission Defends Its Proposal
The European Commission rejects the suggestion that simplification necessarily means weaker financial controls.
Brussels argues that the proposed budget would preserve essential safeguards while improving the efficiency of spending.
National authorities would remain responsible for monitoring expenditure and ensuring compliance with EU requirements.
The Commission would retain powers to request corrections and changes to national plans.
The proposal also includes measures intended to improve transparency, including a centralised system for publishing information about recipients of EU funding.
According to the Commission, the objective is to create a more coherent funding framework without sacrificing accountability.
The disagreement therefore centres on whether the proposed safeguards are sufficiently robust.
The Commission emphasises flexibility and administrative efficiency.
The European Court of Auditors is calling for stronger guarantees that financial transactions remain traceable and independently verifiable.
A Political Battle Over the EU’s Next Seven-Year Budget
The dispute adds another dimension to negotiations over the EU’s next Multiannual Financial Framework.
Member states are already divided over the size of the budget and the distribution of resources between traditional programmes and emerging priorities.
Defence, competitiveness, technological investment, migration and support for Ukraine are placing additional demands on European finances.
At the same time, countries that depend heavily on agricultural and cohesion funding want to preserve substantial allocations for those policies.
The proposed restructuring is intended to reconcile these competing priorities.
However, concerns about transparency could complicate the negotiations.
Governments and the European Parliament will need to consider not only how resources are distributed but also how spending decisions are monitored.
The outcome could shape the European Union’s financial governance for years to come.
What the New Budget Means for Greece
For Greece, the negotiations will have consequences for agriculture, regional development, infrastructure and investment.
EU funding supports a wide range of economic activities, from rural development to major public works.
Changes to the budget structure could affect how Greek authorities design, approve and monitor investment programmes.
Greater flexibility may allow funding to be redirected towards urgent priorities.
However, it could also require stronger national administrative systems and more sophisticated monitoring procedures.
The controversy surrounding agricultural subsidies highlights the importance of reliable data and effective verification.
Greece’s challenge will be to secure sufficient European resources while demonstrating that they can be managed transparently.
The issue is both economic and institutional.
Poor financial controls can undermine public confidence, expose beneficiaries to uncertainty and increase the risk of financial corrections or recovery demands.
The Fundamental Question: Flexibility Without Accountability Gaps?
The European Union faces a difficult balancing act.
Successive crises have demonstrated the need for faster, more adaptable public spending.
Yet the management of hundreds of billions of euros requires clear rules, reliable information and independent auditing.
The European Court of Auditors is warning that broader national discretion must not undermine the ability to establish where EU funds ultimately go.
The Commission maintains that its reforms can combine administrative simplification with stronger transparency.
The negotiations over the 2028–2034 budget will determine how these competing objectives are reconciled.
The central question is not simply how much money Brussels will distribute, but whether European institutions and taxpayers will be able to trace how that money is used.
For Greece and other countries that rely heavily on agricultural and cohesion funding, the answer will be particularly consequential.
Source: pagenews.gr
Διαβάστε όλες τις τελευταίες Ειδήσεις από την Ελλάδα και τον Κόσμο