DBRS:Greece Widens Growth Gap With Europe’s Core—Economy Seen Expanding 1.8% as Unemployment Toward 7.8%
 ΧΡΟΝΟΣ ΑΝΑΓΝΩΣΗΣ 8 '
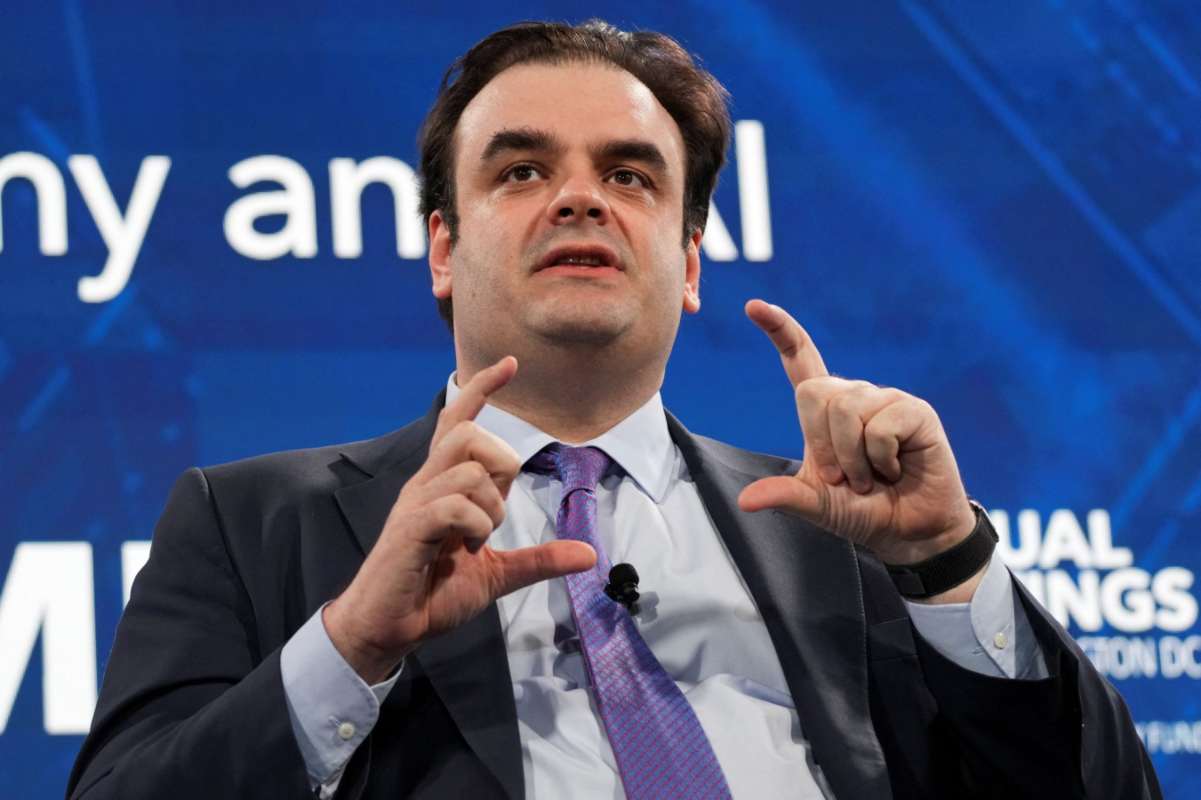
Πηγή Φωτογραφίας: eurokinissi//DBRS: Greece Widens Growth Gap With Europe’s Core — Economy Seen Expanding 1.8% as Unemployment Heads Toward 7.8%


The biggest message in Morningstar DBRS’s latest macroeconomic outlook for Greece is not simply the 1.8% growth forecast.
It is what is happening around Greece.
At a time when Europe is still struggling to generate stronger economic momentum, Greece remains among the economies expanding significantly faster than the euro area’s largest members.
And the comparison becomes more important because the outperformance is expected to extend across two consecutive years.
DBRS forecasts for Greece:
- GDP growth of 1.8% in 2026, a marginal 0.1 percentage-point downgrade from its previous estimate.
- GDP growth of 1.8% again in 2027, unchanged from the previous forecast.
- Unemployment at 8.3% in 2026, 0.1 percentage point below its previous estimate.
- A further decline in unemployment to 7.8% in 2027.
The message, therefore, is not that Greece is entering a period of spectacular economic growth.
It is arguably more important than that:
Greece is maintaining a significant growth premium over Europe’s core economies in an increasingly challenging global environment.
Greece at 1.8%, France at 0.5%: The Gap That Matters
This is where the comparison becomes striking.
For 2026, Morningstar DBRS forecasts:
- Greece: 1.8%
- Germany: 1.0%
- Italy: 0.8%
- France: 0.5%
- Portugal: 2.0%
- Spain: 2.5%
Greece is therefore not expected to be the euro area’s fastest-growing economy.
But it is comfortably ahead of its three largest economies.
Looking at 2026 and 2027 together makes the divergence even clearer.
Based on DBRS’s annual projections, Greece would record roughly 3.6% cumulative real growth over the two-year period, compared with around 2.2% for Germany, 1.5% for Italy and 1.4% for France.
These are approximate calculations based on DBRS’s annual forecasts rather than separate projections published by the rating agency.
But they illustrate the central point:
Greece continues to enjoy a growth premium over Europe’s economic core.
From “Greek Risk” to a Greek Growth Differential
The shift becomes even more significant when viewed through a longer historical lens.
For years, the debate around Greece was dominated by the country’s distance from the rest of Europe in terms of sovereign risk, fiscal credibility and access to financing.
The question is increasingly changing.
It is now becoming:
How much faster can Greece grow than Europe’s largest economies — and for how long?
A 1.8% growth rate is hardly spectacular in isolation.
Against 0.5% in France, 0.8% in Italy and 1% in Germany, however, it carries a very different significance.
For investors, absolute economic performance matters.
But relative performance matters too.
Unemployment Moves Closer to 8%
The second major component of the outlook is the labor market.
Morningstar DBRS expects Greek unemployment to continue falling:
8.3% in 2026 and 7.8% in 2027.
If that forecast materializes, Greece will move closer to unemployment levels that appeared extremely distant during the sovereign debt crisis years.
There is, however, an important caveat.
Despite the improvement, Greece continues to have a relatively high unemployment rate compared with many European economies.
For 2026, DBRS expects even higher rates in several countries, including:
- Finland: 10.3%
- Spain: 10.0%
- Sweden: 8.6%
The Greek labor market therefore tells two stories simultaneously:
a major recovery — and an unfinished convergence process.
Europe Has a Bigger Growth Problem
This may be the broader message emerging from the DBRS outlook.
The rating agency describes advanced economies as resilient but relatively subdued.
Europe in particular remains trapped in a low-growth environment.
Manufacturing continues to struggle, competition from Asia is intensifying and energy costs remain a structural challenge for European industry.
This creates a paradox for Greece.
The country can continue outperforming the European average, but it cannot fully decouple from a Europe that is barely growing.
Germany, France and Italy are major trading partners and important sources of investment, tourism and economic demand.
Persistent weakness in those economies eventually has consequences beyond their borders.
The New Global Economy Is Investing in Three Things
DBRS also identifies a major shift in global capital expenditure, describing the current environment as a kind of “technology arms race.”
Capital is increasingly being directed toward three major areas:
- Artificial intelligence and technology
- Energy infrastructure and power networks
- Defense and the defense industry
At the same time, protectionism, reshoring and efforts to reduce dependence on vulnerable global supply chains are creating another wave of investment demand.
That can support global growth.
But there is another side to the story.
Governments and companies are competing for enormous amounts of capital at the same time.
When sovereigns, technology giants, energy companies and defense manufacturers are all seeking long-term financing, pressure on bond yields and borrowing costs can increase.
US at 2.1%, India at 6.7%
The global picture also highlights how sharply economic speeds are diverging.
DBRS forecasts:
United States: 2.1% growth in 2026 and 2.1% in 2027.
China: 4.6% in 2026.
India: 6.7% in 2026.
Against those numbers, Europe’s challenge becomes even more obvious.
The question is no longer simply whether Europe can avoid recession.
It is whether the continent risks becoming trapped in a prolonged period of growth around 1%, while the United States and Asia invest aggressively in the technologies, energy systems and industrial capabilities that could define the next decade.
Greece’s Biggest “But”: The Strait of Hormuz
This is where the positive Greek outlook collides with the biggest threat identified by DBRS.
Energy.
The agency says risks to the global economic outlook remain tilted to the downside, with particular attention focused on developments around the Strait of Hormuz.
The strategic importance of the waterway is enormous.
It is not simply another geopolitical flashpoint.
It is one of the world’s most important transit routes for oil and LNG.
A serious disruption to energy flows can trigger a chain reaction:
Oil → natural gas → inflation → interest rates → consumption → growth.
And that chain matters directly for Greece.
The Irony Behind the 1.8%
This is perhaps the most interesting way to read the DBRS assessment.
Greece is outperforming Europe’s core economies in terms of expected growth.
At the same time, it remains an economy exposed to energy costs through transportation, tourism, household consumption and energy-intensive business activity.
A prolonged energy shock can therefore hit several parts of the economy simultaneously:
household disposable income, corporate margins, transport costs, inflation and ultimately consumer spending.
DBRS is effectively delivering two messages about Greece.
The first is encouraging:
The Greek economy is still growing faster than Europe’s core.
The second is a warning:
The 1.8% forecast is not insulated from another major energy shock.
The Real Test Comes in 2027
The forecast of 1.8% growth again in 2027 is ultimately more significant than the number may initially suggest.
It indicates that DBRS does not see Greece’s relative economic strength simply as a one-year phenomenon.
But the agency’s broader outlook also illustrates how quickly the external environment can change.
Greece now faces a very different economic challenge from the one it confronted a decade ago.
It is no longer simply trying to prove that it can grow.
The challenge is to preserve its growth advantage while Europe slows and energy becomes more expensive.
And that may ultimately be the real economic story behind Morningstar DBRS’s 1.8% forecast.
Source: pagenews.gr
Διαβάστε όλες τις τελευταίες Ειδήσεις από την Ελλάδα και τον Κόσμο