Europe’s Winter Arithmetic: Why 2026 Is Not a Rerun of 2022
 ΧΡΟΝΟΣ ΑΝΑΓΝΩΣΗΣ 9 '
Πηγή Φωτογραφίας: AP Photo//Europe’s Winter Arithmetic: Why 2026 Is Not a Rerun of 2022


Europe is heading into the winter of 2026 with a dangerous sense of familiarity.
Gas prices are rising. Storage levels are lower than in previous years. Brussels is again asking governments to curb demand.
It looks like 2022.
But this is not 2022.
Back then, Europe faced one dominant problem: the loss of Russian pipeline gas.
Today, the energy shock is far more complex. Shipping through the Strait of Hormuz remains constrained, Bab el-Mandeb is under pressure, part of Qatar’s LNG capacity has been damaged, and Europe’s diesel market is already trading at extreme levels.
Above all, there is a new risk from across the Atlantic: Donald Trump has said he supports restricting, or potentially banning, US diesel exports. The Treasury Department is examining whether a full or partial restriction is feasible.
Brussels Reaches for the 2022 Playbook
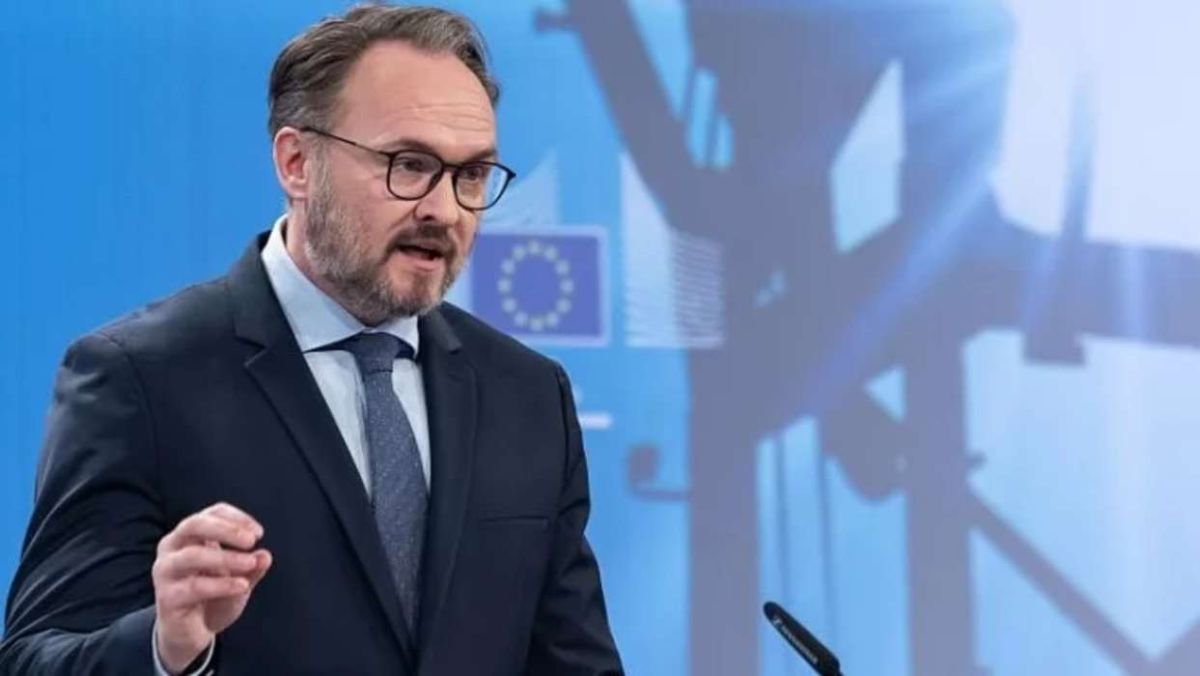
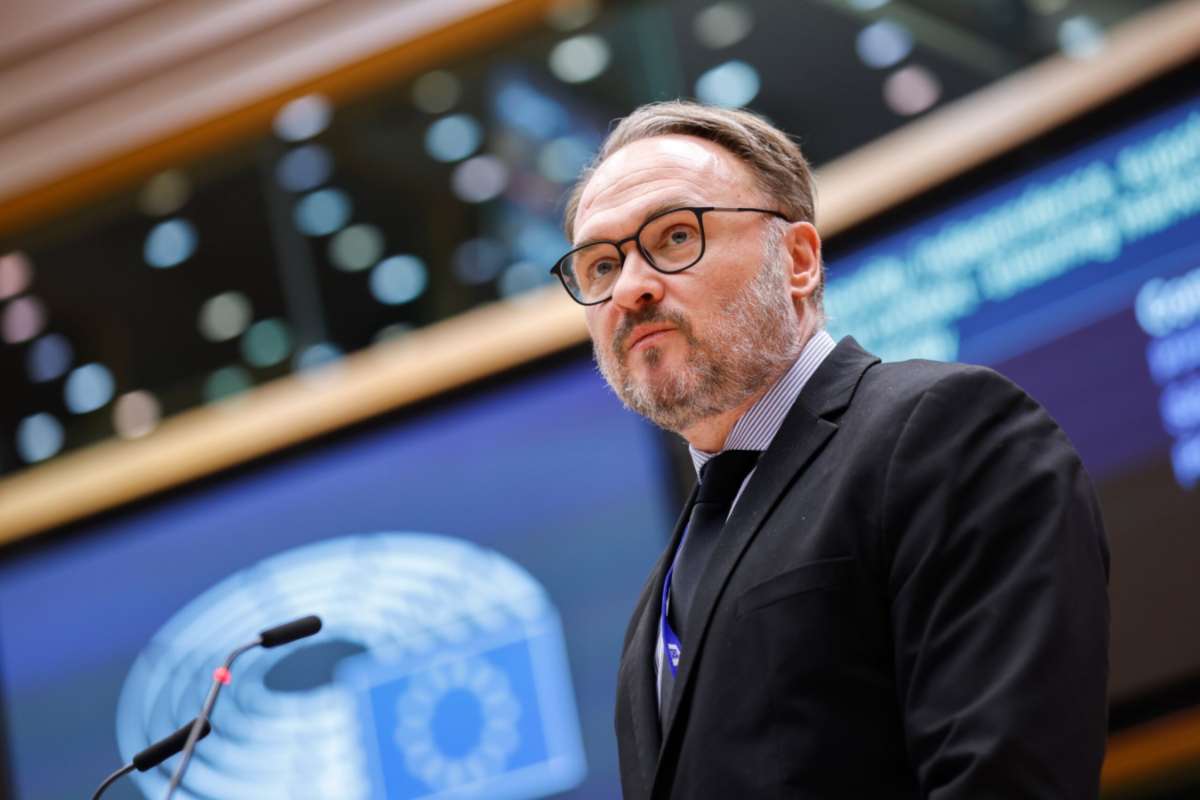
On September 25, EU Energy Commissioner Dan Jørgensen warned member states of what he described as a “price crisis linking to a supply crisis.”
The proposed responses sounded familiar:
- keep injecting gas into storage,
- reduce electricity consumption during peak hours,
- lower temperatures in public buildings,
- switch off unnecessary public lighting.
The European Commission has stressed that there is no immediate physical shortage of gas, but rising prices and tighter global LNG markets are increasing the risks ahead of winter.
Storage Is Lower — But Europe Is Not Empty
An important distinction matters.
As of September 27, European gas storage facilities were roughly 70.9% full, according to Gas Infrastructure Europe. Germany was at about 57.4%, the Netherlands at 57.5% and Italy at 86.6%.
Europe is therefore not facing an immediate shortage.
But it is entering winter from a weaker position than in recent years.
And the problem is compounded by the fact that additional LNG must now be bought in a global market where supply has already tightened.
Qatar Has Lost Part of Its LNG Capacity
The Middle East has changed the energy equation.
Around 17% of Qatar’s production capacity at Ras Laffan was taken offline after strikes during the conflict. Two LNG trains could require years to return fully to service, according to the latest estimates from Qatar.
That matters because Qatar is one of the largest suppliers in the global LNG market.
Europe can still buy more gas.
But to do so, it must compete for the same cargoes with:
- China,
- Japan,
- South Korea,
- other major Asian importers.
Storage does not create new molecules of gas.
It simply determines who is willing to pay more for them.
The Bigger Problem May Not Be Gas
The real difference from 2022 may be diesel.
On September 15, physical diesel prices in northwest Europe reached $1,642.25 per tonne, the highest level recorded by Platts for that market.
In the Mediterranean, prices reached $1,664.75 per tonne.
There is no single cause.
Instead, Europe is dealing with a combination of:
- low inventories,
- reduced Russian exports,
- shipping disruptions,
- refinery constraints,
- instability in the Middle East.
S&P Global has described the situation as a deepening supply crisis in middle distillates.
Why Diesel Is Different From Gas
Gas demand can be cut relatively quickly.
Households can turn down heating.
Some industrial users can reduce production.
Power generators can sometimes switch fuels.
Diesel is much less flexible.
It powers:
- trucks,
- farming equipment,
- construction,
- logistics,
- industrial generators,
- parts of the shipping sector.
Reducing diesel consumption often means reducing actual economic activity.
And that is why higher diesel prices pass quickly into the wider economy:
transport → food → construction → retail.
The US Risk
Into this already tight market comes Washington.
Trump has said he wants officials to examine a ban on diesel exports in an attempt to lower prices for American consumers.
“I’ve called for it,” he said, while Treasury Secretary Scott Bessent confirmed that both full and partial restrictions are being examined.
The political rationale is clear.
US diesel prices have surged, putting pressure on:
- farmers,
- truckers,
- businesses in inland states.
But analysts warn that an export restriction could temporarily reduce US prices while pushing prices higher elsewhere and generating new global inflationary pressure. For Europe, that matters greatly.
In an already constrained market, US exports are an important alternative source of refined products.
Europe Has One Tool That Matters More This Time
Emergency oil stocks.
EU rules require countries to hold reserves equivalent to at least:
90 days of net imports or 61 days of domestic consumption, depending on the applicable obligation.
The 2026 crisis has already triggered the largest coordinated stock release in the history of the International Energy Agency.
In March, the IEA’s 32 member countries agreed to make 400 million barrels available to the market.
And there is one especially important European detail:
while the global release was weighted heavily toward crude, the IEA said European contributions would come largely from refined products.
That means Europe already has a mechanism that can target the market where the pressure is most acute.
Crude and Diesel Are Not the Same Thing
This distinction is crucial.
If the shortage is in refined products, releasing more crude does not have the same immediate effect.
The crude still has to:
- be transported,
- find available refinery capacity,
- be processed into diesel,
- be distributed to the markets where shortages are most severe.
Europe is already operating with tight refining capacity.
That makes the composition of strategic reserves almost as important as their total size.
Brussels Already Knows the Rules Need Updating
The European Commission has already begun reviewing the Oil Stocks Directive.
Its own rationale is telling: the Middle East crisis exposed weaknesses in the current system.
The Commission is considering whether Europe needs specific stockholding requirements for individual petroleum products, rather than treating crude and refined fuels largely as one emergency buffer.
That could eventually mean larger dedicated reserves of:
- diesel,
- jet fuel,
- other critical distillates.
The Difficult Trade-Off
Using emergency stocks is not cost-free.
If Europe releases large quantities over winter and:
- Hormuz remains constrained,
- the conflict continues into 2027,
- US exports are restricted,
then Europe will have reduced its emergency buffer just as it may need it most.
A stock release is therefore a trade-off:
less pressure today in exchange for less insurance tomorrow.
Europe Is Still Better Prepared Than in 2022
There is also a more positive side.
Europe is better prepared in several respects than it was four years ago.
The Commission points to:
- more diversified gas supplies,
- greater LNG import capacity,
- structurally lower gas demand,
- significant commercial and strategic reserves.
That is why Brussels is not currently warning of imminent physical shortages.
The bigger risk is price, not outright absence of energy.
And prolonged high prices can be just as damaging for European industry.
Three Ways the Winter Could Break
1. Expensive, but manageable
If there is partial de-escalation in the Middle East and Washington stops short of a full diesel export ban, Europe could get through winter without physical shortages.
But it would still face:
- high fuel prices,
- persistent energy inflation,
- higher logistics costs,
- less room for the ECB to cut rates.
2. US diesel exports disappear
This is the more difficult scenario.
If Washington significantly limits exports while Middle Eastern shipping remains disrupted, Europe’s diesel market could suffer another sharp price shock.
Governments would then face choices such as:
- fuel-tax cuts,
- targeted subsidies,
- strategic stock releases,
- temporary demand measures.
3. A Middle East deal
De-escalation could push crude prices down quickly.
But diesel might not follow at the same speed.
Europe’s refining deficit and the tight middle-distillate market would not disappear just because Brent falls.
That is perhaps the most important distinction between crude oil and finished fuels.
This Winter May Be Decided in Refineries, Not Just Gas Storage
In 2022, Europe had to replace one dominant gas supplier.
In 2026, it is trying to manage:
LNG + Hormuz + the Red Sea + refinery capacity + diesel + US energy policy.
Gas-saving measures still matter.
But they do not solve the transport-fuel problem.
And that may become the defining issue of the winter.
Europe has a large energy buffer in its emergency stocks. How much of it is released, when, and in what form may prove just as important as how full its gas storage facilities are.
Because the winter of 2026 may not be decided only in gas caverns. It may be decided in diesel tanks.
Source: pagenews.gr
Διαβάστε όλες τις τελευταίες Ειδήσεις από την Ελλάδα και τον Κόσμο