France’s Debt Crisis Shakes the Eurozone: Bond Yields Surge as Banks and Greek Stocks Tumble
 ΧΡΟΝΟΣ ΑΝΑΓΝΩΣΗΣ 15 '
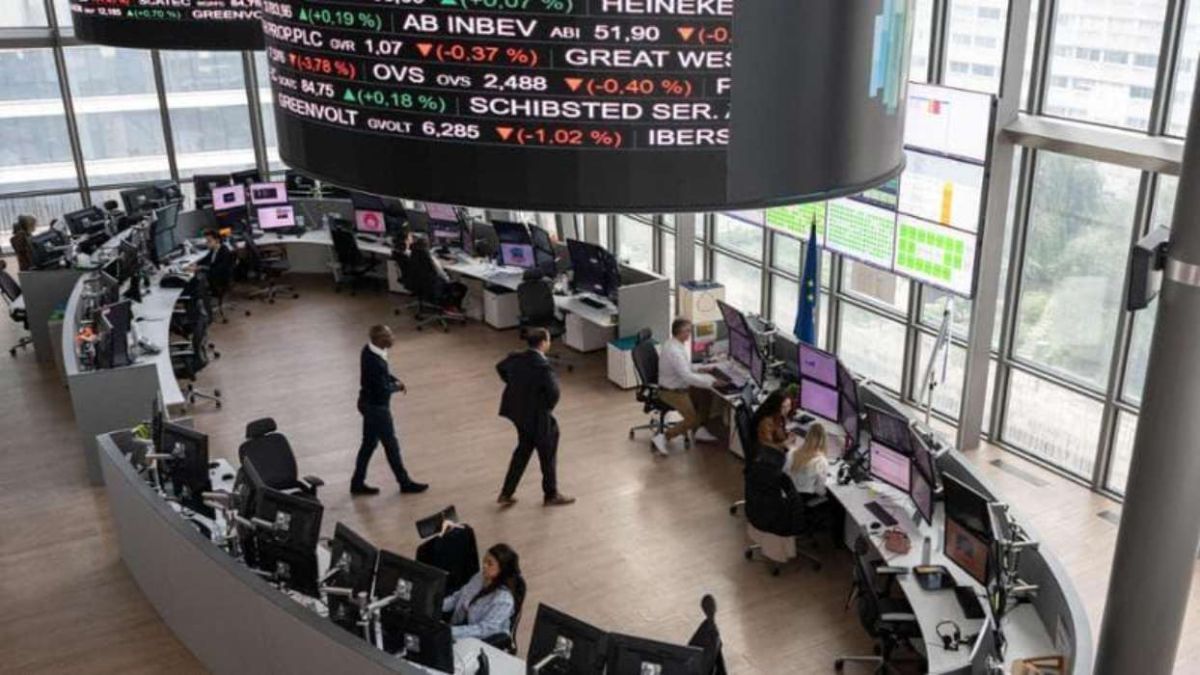
Πηγή Φωτογραφίας: AP Photo//France’s Debt Crisis Shakes the Eurozone: Bond Yields Surge as Banks and Greek Stocks Tumble


La situation est désespérante. The situation is deeply troubling for the eurozone, with France at the center of a financial-market storm combining fiscal uncertainty, political instability, rising energy costs and mounting pressure on sovereign debt.
The turmoil is no longer confined to French government bonds.
It is spreading across European banking stocks, equity markets and government borrowing costs as investors reassess risks that had previously received less attention.
Greece has also been caught in the sell-off. The Athens Stock Exchange recorded a second consecutive session of substantial losses, with banks bearing the brunt of the pressure.
The timing is particularly difficult.
Bond yields are rising just as oil prices climb, threatening to reignite inflation and complicate monetary policy.
The European Central Bank now faces a difficult balancing act: how to safeguard financial stability without undermining its commitment to price stability.
France at the Center: The 10-Year Yield Reaches 4.85%
France’s 10-year government bond yield reached 4.85%, according to market figures cited for Thursday, October 8, 2026.
The level reflects a significant increase in the French government’s borrowing costs.
The pressure comes amid growing concerns about the country’s fiscal outlook and the political difficulties surrounding approval of its budget.
The French government is attempting to reduce its budget deficit while facing strong opposition to proposed public-spending cuts of approximately €45 billion.
Social protests and political disagreements have made the task increasingly complicated.
For investors, the central concern is whether France can deliver a credible fiscal adjustment without triggering further political instability.
When uncertainty rises over a government’s ability to implement its fiscal plans, investors may demand higher yields to compensate for the perceived risk.
France’s position makes the situation particularly important for the eurozone.
As one of the European Union’s largest economies, France plays a central role in the region’s financial system, while French government securities are widely held by banks, insurers and institutional investors.
The Warning Signal: France’s Spread Over Germany Widens to 137 Basis Points
Germany’s 10-year government bond yield stood at 3.48%.
That placed the spread between French and German 10-year bonds at 137 basis points.
The spread represents the additional yield investors require to hold French rather than German sovereign debt.
German government bonds remain a key benchmark for eurozone debt markets.
A widening spread can signal growing concerns about a country’s fiscal position, political stability or financing outlook.
The development does not automatically mean that France is facing a sovereign debt crisis.
It does, however, indicate that investors are demanding a higher risk premium.
The question is whether the widening reflects a temporary period of market volatility or a more persistent deterioration in confidence.
Sovereign Bond Yields: A Snapshot of Global Pressure
According to the market figures provided for the session:
- France: 4.85% — At the center of fiscal and political uncertainty.
- Germany: 3.48% — Rising yields even in the eurozone’s benchmark bond market.
- United States: 5.28% — Significant pressure in the US Treasury market.
- Greece: 4.46% — Exposed to the broader increase in global borrowing costs.
The figures illustrate that higher bond yields are not exclusively a French phenomenon.
Markets across major economies are adjusting to inflation risks, monetary-policy expectations and substantial government financing needs.
However, the underlying causes differ.
In France, political uncertainty and fiscal credibility are particularly important.
In the United States, Treasury yields also reflect expectations for Federal Reserve policy, inflation and government debt issuance.
For Greece, higher global yields can increase the cost of new borrowing even when domestic fiscal fundamentals remain unchanged.
The Shadow of 2010: Why Comparisons Require Caution
France’s bond-market turmoil has prompted comparisons with the European sovereign debt crisis that began in 2010.
The analogy reflects concerns about financial contagion, particularly the possibility that pressure in one sovereign bond market could spread to others.
However, the current situation is not identical to the crisis of the previous decade.
The eurozone now has different financial supervision arrangements and additional mechanisms designed to address severe market disruption.
France’s debt structure, financing conditions and economic position also differ substantially from those of Greece during the earlier crisis.
The historical comparison therefore serves primarily as a warning about the consequences of a prolonged loss of market confidence.
It should not be treated as evidence that France is experiencing a crisis equivalent to Greece’s in 2010.
The ECB Faces a Difficult Monetary Policy Dilemma
Rising sovereign bond yields create a complex challenge for the European Central Bank.
On one hand, the ECB’s primary mandate is to maintain price stability.
On the other, severe disruptions in government bond markets can affect financial stability and interfere with the transmission of monetary policy across the eurozone.
Market participants have discussed the possibility of an ECB intervention, potentially as early as October.
However, no official decision to launch a new bond-purchasing program has been established by the information available here.
Speculation about intervention should not be confused with an announced policy measure.
The ECB has instruments that may be used, subject to specific conditions, to address unwarranted disruptions in monetary-policy transmission.
Whether those instruments are appropriate depends on the nature of the market stress and the relevant institutional criteria.
Oil Near $105 Adds Another Inflationary Threat
The sovereign debt turmoil is unfolding alongside renewed pressure in energy markets.
Oil prices reportedly moved from around $101 a barrel on Wednesday evening toward $105 on Thursday.
Higher oil prices can increase transportation, production and operating costs across the European economy.
If sustained, those increases may eventually feed into consumer prices.
The eurozone is particularly sensitive to energy shocks because many industries and transportation activities depend on imported fuels.
Higher energy costs can squeeze corporate profit margins while reducing household purchasing power.
This creates a difficult environment for monetary policymakers.
An economy experiencing both elevated inflation and slowing activity leaves central banks with fewer straightforward policy options.
Easing monetary conditions may help economic activity and financial markets, but it can also complicate efforts to contain inflation.
European Banks Move to the Front Line of the Sell-Off
Banking stocks have come under particular pressure as government bond markets experience sharp fluctuations.
Banks hold sovereign bonds and depend on the orderly functioning of wholesale funding markets.
When bond yields rise, the market prices of existing fixed-rate bonds generally fall.
This can create valuation losses in securities portfolios, depending on their accounting treatment and risk-management arrangements.
Higher yields may also increase funding costs.
The impact on profitability is not necessarily one-directional.
Higher interest rates can support some sources of net interest income.
However, they may also increase borrowing costs for households and companies, potentially weakening credit quality.
This combination helps explain why bank shares often experience significant volatility during periods of sovereign bond-market stress.
European Equities Retreat as Financial Stocks Lead Losses
European stock markets recorded further declines during Thursday’s session.
Shortly after 5 p.m. Greek time, Germany’s DAX was down 0.7%.
France’s CAC index had fallen 0.15%, while Italy’s FTSE MIB was lower by 0.6%.
The Euro Stoxx 50 was trading approximately 0.4% lower.
The declines reflected a broader reassessment of risk across European equities.
In Paris, some buyers emerged to absorb the initial selling pressure.
However, the relatively modest decline in the French equity benchmark did not necessarily indicate an easing of the country’s fiscal problems.
Stock and bond markets respond to different factors and do not always move in the same direction.
Wall Street Is Not Immune
The pressure on government borrowing costs extends beyond Europe.
At the beginning of the US trading session, the Dow Jones Industrial Average was marginally lower.
The S&P 500 had declined 0.28%, while the Nasdaq was down 0.6%.
The US 10-year Treasury yield stood at 5.28%.
Higher bond yields can weigh on equity valuations because they raise the discount rate applied to expected future earnings.
The effect can be particularly pronounced for companies whose valuations depend heavily on long-term growth expectations.
Investors also compare the potential returns from equities with the yields available on government securities.
When sovereign bond yields rise sharply, the relative attractiveness of different asset classes can change.
The Euro Holds Near $1.12
In foreign exchange markets, the euro was trading near $1.12.
The exchange rate suggested that the turmoil in sovereign debt markets had not, at that point, produced a comparably sharp move in the single currency.
However, the euro’s direction depends on several factors.
Expectations for ECB and Federal Reserve interest rates, economic growth prospects and differences in bond yields all influence currency markets.
Widening interest-rate differentials can affect international capital flows.
At the same time, increased volatility may encourage companies and institutional investors to expand currency hedging.
The evolution of France’s fiscal situation and future central-bank decisions will remain important for the euro’s outlook.
Athens Stock Exchange: A Second Session of Heavy Losses
The Greek stock market suffered another difficult session.
The Athens Stock Exchange General Index closed Thursday at 2,568.05 points, down 2.06%.
It was the second consecutive session of substantial losses.
During trading, the index fell as low as 2,540 points.
Buyers emerged toward the end of the session, helping the benchmark recover part of its earlier decline.
The late rebound did not reverse the overall negative picture.
Selling pressure remained strong, while total trading turnover reached €622 million.
The unusually high turnover reflected significant portfolio activity.
However, turnover alone does not establish that all the transactions represented foreign investors withdrawing capital from Greece.
Greek Banks Slide 3.61% as Trading Reaches €300 Million
Banking shares led the decline in Athens.
The banking index fell 3.61%.
Approximately €300 million worth of shares changed hands across Greece’s four systemic banks.
That represented nearly 48% of total market turnover.
The concentration highlights the banking sector’s central role in the session.
Greek banks are sensitive to European interest-rate expectations, international funding conditions and changes in investor risk appetite.
A sharp decline in their share prices does not automatically imply a deterioration in their capital adequacy.
Nevertheless, the scale of the sell-off shows that investors viewed the sector as particularly exposed to changes in the broader financial environment.
Only 17 Stocks Rise as 102 Finish Lower
The breadth of the sell-off was striking.
Only 17 stocks closed the session higher.
By contrast, 102 stocks ended in negative territory.
That represented almost six declining shares for every advancing share.
The imbalance indicates that selling pressure extended well beyond the banking sector.
The FTSE 25 large-cap index fell 2.16%.
The mid-cap index declined 2.43%.
Simultaneous losses across different market segments suggest a broad reduction in risk appetite during the session.
The Stocks That Showed Greater Resilience
Despite the negative market environment, some companies displayed relative resilience.
Among large-cap non-bank stocks, PPC, Allwyn, Motor Oil, Hellenic Petroleum and Coca-Cola HBC performed comparatively better.
Shipping companies Safe Bulkers and Star Bulk also showed stronger relative performance.
In the small- and mid-cap segments, Sarantis, Trastor and Austriacard stood out.
Their performance does not mean they were unaffected by the broader market turmoil.
It does, however, demonstrate that investors continued to differentiate between individual companies even during a widespread sell-off.
What Greece’s 4.46% Bond Yield Means for the Economy
Greece’s 10-year government bond yield stood at 4.46%.
The figure reflects the wider increase in borrowing costs across international debt markets.
For the Greek government, higher yields can increase the cost of issuing new debt.
However, the impact does not immediately extend to the entire existing public debt stock.
The maturity profile of outstanding debt and the share carrying fixed interest rates are important factors.
The Greek economy can also be affected through banks and businesses.
When financing costs rise internationally, companies may eventually face more expensive access to credit and capital markets.
This matters particularly for investment projects requiring substantial debt financing.
The broader economic consequences will depend on how long higher yields persist and whether market conditions stabilize.
The Bigger Risk: Contagion From France to the Wider Eurozone
The central concern for investors is the possibility of contagion.
France is one of the European Union’s largest economies.
Its government bonds are held by banks, insurers, investment funds and other institutional investors across Europe and beyond.
A prolonged rise in French sovereign yields could affect the market value of those holdings.
If the turmoil also undermines confidence in sovereign bonds more broadly, borrowing costs in other eurozone countries could increase.
Contagion, however, is not inevitable.
Its extent depends on fiscal developments, investor confidence, the resilience of financial institutions and the response of European authorities.
The distinction matters: elevated market volatility is a warning sign, but it is not itself proof of an imminent systemic financial crisis.
Three Factors Will Shape the Next Market Sessions
Investors are watching three developments particularly closely.
First, France’s political and fiscal response.
The government’s ability to secure agreement on a credible budget will influence expectations for public finances and borrowing costs.
Second, the direction of oil prices.
Sustained energy inflation could increase pressure on households and businesses while complicating central-bank policy.
Third, the ECB’s assessment of financial conditions.
Markets will be looking for signs of whether policymakers consider the rise in yields a normal repricing of risk or a threat to the smooth transmission of monetary policy.
The interaction of these three factors will help determine whether the current turbulence subsides or persists.
The Eurozone’s Difficult Balancing Act
The market turmoil highlights the close relationship between fiscal policy, banking stability and energy costs.
France is under pressure because of political uncertainty and rising sovereign borrowing costs.
Higher oil prices threaten to add to inflation.
European banks are experiencing increased equity-market volatility.
And the Athens Stock Exchange is feeling the effects of weaker international risk appetite.
The eurozone’s central challenge is to prevent fiscal and political turbulence from developing into a broader financing crisis.
Such an outcome is not predetermined.
Nevertheless, sovereign bond yields, banking stocks and energy prices show that investors are reassessing risks more aggressively.
For Greece, the message is clear: domestic financial markets remain closely connected to developments across the European economy.
The path toward stabilization will depend on political developments in France, conditions in sovereign debt markets and the direction of global energy prices.
Source: pagenews.gr
Διαβάστε όλες τις τελευταίες Ειδήσεις από την Ελλάδα και τον Κόσμο