Europe Pushes Back on Trump Over Diesel: “We Won’t Empty Our Reserves Under Pressure”
 ΧΡΟΝΟΣ ΑΝΑΓΝΩΣΗΣ 6 '
Πηγή Φωτογραφίας: AP Photo//Europe Pushes Back on Trump Over Diesel: “We Won’t Empty Our Reserves Under Pressure”


The transatlantic dispute over diesel has entered a new phase.
According to POLITICO, European governments agreed that they need a more assertive response to Washington after the Trump administration intensified pressure for a major release of European strategic diesel reserves.
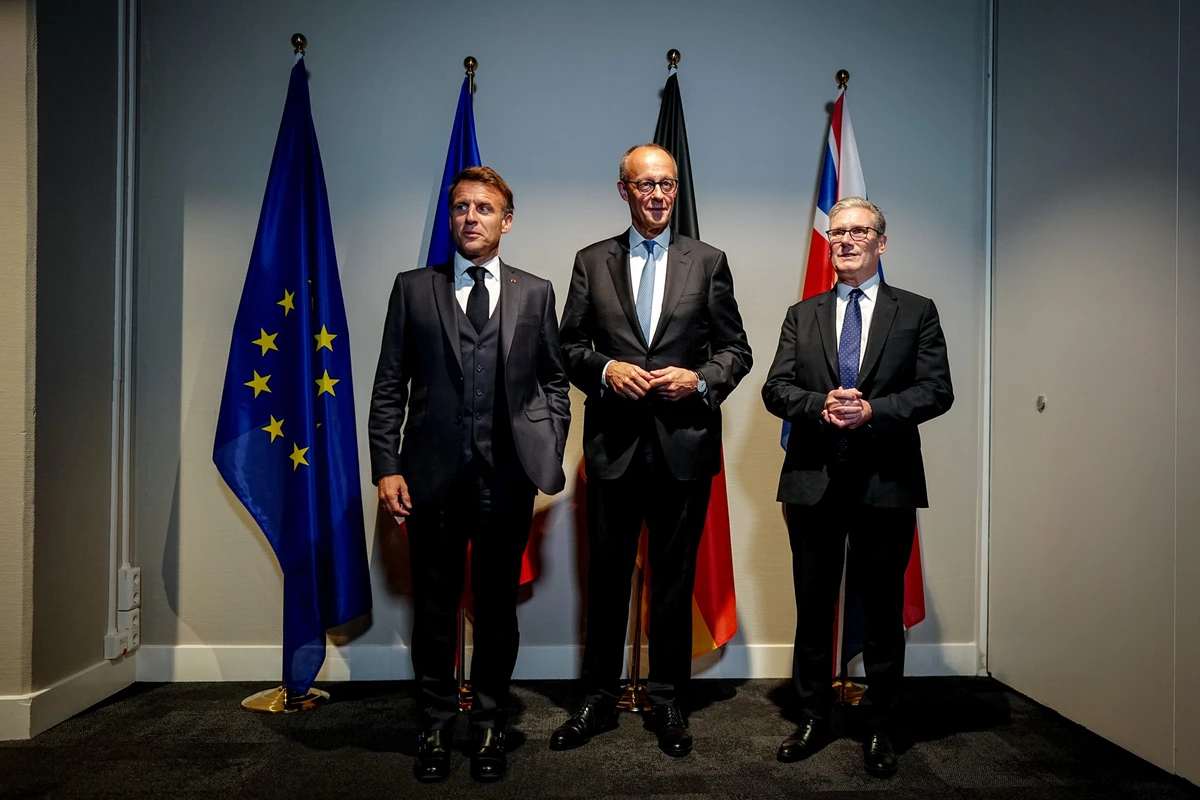
Britain, France and Germany were among the countries involved in emergency discussions over how to respond without weakening Europe’s own energy-security buffer.
The dispute is no longer simply about fuel stocks.
It is increasingly about who should bear the cost of the global diesel shortage.
Washington wants a major European release
The U.S. administration has been pressing European governments to release roughly 120 million barrels of fuel stocks over six months, according to reports cited by the Financial Times and other outlets.
Washington’s argument is that a coordinated release could:
increase global supply,
push prices lower,
and reduce pressure for a U.S. export ban.
European governments, however, do not necessarily see those options as equivalent.
Europe’s message: emergency stocks are not a U.S. price-management tool
The central European argument is that strategic stocks exist primarily for a serious supply disruption.
They are not meant simply to manage American retail fuel prices.
The Trump administration is under pressure over diesel costs in the United States, where higher prices affect:
trucking,
agriculture,
industry,
and transport.
But Europe has its own risk calculation.
The key question: what happens if there is a second shock?
That is why European governments are resisting a very large release.
If Europe uses a substantial share of its emergency stocks now, what happens if there is another disruption involving:
the Strait of Hormuz,
refining capacity,
winter demand,
or an actual reduction in U.S. exports?
Strategic reserves can only be released once before they need to be replenished.
That makes governments reluctant to draw them down aggressively while geopolitical uncertainty remains high.
The threat of a U.S. export ban changes the tone
The most sensitive issue is that U.S. pressure on Europe has been accompanied by debate in Washington over possible restrictions on diesel exports.
The Trump administration has considered such a step as a way of boosting domestic supply and easing U.S. prices.
For European capitals, that creates a difficult equation:
Washington is asking Europe to release its emergency stocks while simultaneously considering measures that could reduce the flow of U.S. diesel to Europe.
That is where the political tension is coming from.
Why an export ban would matter so much for Europe
Europe remains significantly dependent on imported refined products.
Diesel is particularly sensitive because it is not just a fuel for cars.
It is central to:
road freight,
logistics,
agriculture,
construction,
industry,
and in some countries heating.
A sharp reduction in U.S. supply could therefore quickly feed through into:
transport costs,
food prices,
industrial costs,
and inflation.
It could also backfire on the U.S.
Market analysts have also questioned whether a U.S. export ban would actually achieve what the administration wants.
Restricting exports might initially increase domestic availability, but it could also create:
storage bottlenecks,
refinery imbalances,
and broader distortions in fuel markets.
That is one reason some analysts argue that coordinated releases may be less disruptive than outright export restrictions.
Hormuz remains at the heart of the problem
The diesel dispute did not emerge in isolation.
The market has already been hit by serious disruption linked to the Middle East and the Strait of Hormuz.
That has tightened crude and refined-product markets at the same time.
Strategic stocks have already become a central policy tool.
That matters because European governments do not know whether the next disruption will hit:
crude oil,
diesel,
jet fuel,
or natural gas.
Europe does not necessarily oppose a release
The European position is not simply “no.”
Governments are discussing whether some release may be justified.
The real argument is over:
how much, when, and under what conditions.
That distinction is important.
POLITICO describes the emerging line as assertive, not as a break with Washington.
France has already signaled a tougher position
France has supported the idea of coordinated international action through institutions such as the G7, while also opposing U.S. measures that could shift more of the burden onto allies.
That captures the broader European position:
yes to coordinated intervention,
no to unilateral U.S. steps that leave Europe more exposed.
From energy partnership to energy leverage
There is a broader geopolitical issue behind the dispute.
Since 2022, the United States has become one of Europe’s most important energy suppliers.
That strengthened Europe’s energy security.
But it also created a new dependency.
The current diesel dispute shows the limits of that relationship when U.S. and European domestic priorities diverge.
The real issue: who pays for the crisis?
The dispute can be reduced to a simple exchange.
Washington says:
release more European stocks so global prices can fall.
Europe says:
do not ask us to run down our strategic buffer while you are considering reducing your own exports.
That is not just a technical argument over barrels.
It is a negotiation over who absorbs the risk of the energy crisis.
A firmer European line
Britain, France and Germany are not signaling a desire for confrontation with the United States.
But the line described by POLITICO is clearly harder than before:
Europe’s energy security cannot become a variable in a U.S. strategy aimed primarily at lowering domestic diesel prices.
That could become a major new issue in transatlantic energy relations.
The question is no longer whether the U.S. and Europe remain allies.
It is how evenly they share energy risk when their interests no longer fully align.
Source: pagenews.gr
Διαβάστε όλες τις τελευταίες Ειδήσεις από την Ελλάδα και τον Κόσμο